Getting the transcript
Reading the captions from YouTube. A video nobody has opened here before takes 10 to 30 seconds; this page fills in on its own.
Getting the transcript
Reading the captions from YouTube. A video nobody has opened here before takes 10 to 30 seconds; this page fills in on its own.
Ben Felix · @BenFelixCSI
Where viewers went back to watch this video again, from YouTube's public Most replayed graph, lined up with what was said at that moment.
Most replayed moment #1
8:253.9x the video's typical replay level
reasonable. The Avantis CIBC All Equity Asset Allocation ETF has an annual management fee of 0.28%. This is not the MER, to be clear, the management expense ratio, which includes other costs and taxes in it. For example, XEQT has a management fee of
Said at 8:17
Most replayed moment #2
2:483.5x the video's typical replay level
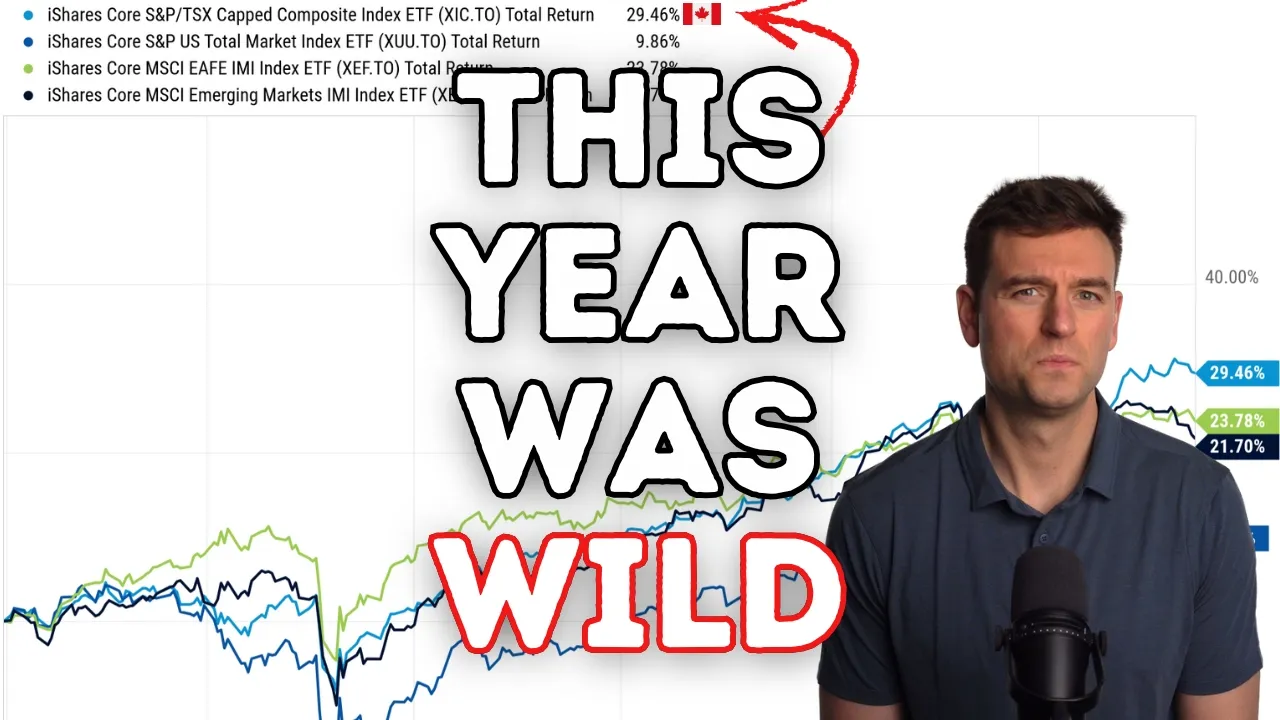
market index fund had returned 29.46% since January 1st, 2025, placing it ahead of international developed and emerging markets and more than tripling the Canadian dollar return on a US total market index fund. Missing a big year
Said at 2:42
Most replayed moment #3
8:592.9x the video's typical replay level
got built-in tilts toward small-cap, value, and high-profitability stocks. Based on the preliminary prospectus, it will have a long-term strategic asset mix of 45% US stocks, 32% Canadian, 15% international developed, and 8% emerging
Said at 8:53
The graph counts replays. It does not show where viewers stopped watching.
Words
3,497
Runtime
18:42
Speaking pace
187wpm
Reading time
15min
187 words per minute, between the 181 median and the 201 75th percentile of 349 measured videos. That distribution comes from the 349-video hook study.
Opening (first 30 seconds)
This year was nuts, both in markets, which I'll get into in a minute, and personally for me. I had testicular cancer, down to one testicle now. I had surgery on the same day in January that PWL Capital, the firm that I've worked for for 12 years, announced it had been acquired by 1 Digital. We were previously a small privately owned Canadian firm, now owned by a much larger American firm. As a PWL Capital shareholder and employee, the acquisition was actually good news and it's unleashed PWL's potential to improve our
94 words, the words spoken in the first 30 seconds at 187 words per minute.
Free, no signup. See how the first 30 seconds hold attention, with rewrites.
Sentence shape
| Measure | This transcript |
|---|---|
| Sentences | 172 |
| Average words per sentence | 20.3 |
| Longest sentence | 61 words |
| Questions asked | 3 |
| Sentences containing a number | 44 |
Most used terms
Filler phrases
37 in total: like 19 · uh 10 · actually 3 · kind of 2 · I mean 1 · basically 1 · literally 1.
A literal whole-word count of the same phrase list the Prepublish browser extension uses, so a phrase inside another word is not counted and a phrase used in its ordinary sense still is. It is a count and not a judgement.
Free, no account. See where attention is likely to drop, with a rewrite for each weak line. The free check shows the scores and the one issue costing the most. Or run it on the words above first.
Free · No login · See a sample audit first if you prefer.
What this transcript is
Every word below is the caption track YouTube publishes for this video, pulled from the video itself and reproduced unchanged. It is not Prepublish's writing, not a summary, and not a re-transcription: it is the video's own published captions. English captions, generated automatically by YouTube, in the video’s original language. Source: the video on YouTube. A channel that would rather this page did not exist can ask for its removal through the contact page, and it is removed.
This year was nuts, both in markets, which I'll get into in a minute, and personally for me. I had testicular cancer, down to one testicle now. I had surgery on the same day in January that PWL Capital, the firm that I've worked for for 12 years, announced it had been acquired by 1 Digital. We were previously a small privately owned Canadian firm, now owned by a much larger American firm. As a PWL Capital shareholder and employee, the acquisition was actually good news and it's unleashed PWL's potential to improve our offering and expand across Canada, which has been a ton of fun.
Okay, my personal news aside, 2025 was a wild ride. Early in the year, it looked like we were in for a bad time, but things turned around and returns in stocks, gold, Bitcoin, and real estate were not what anyone was expecting. I'm Ben Felix, Chief Investment Officer at PWL Capital, and I'm going to tell you what we can learn from 2025. I want to say a quick thank you to everyone watching this channel. It had by far the most views and largest increase in subscribers since I started posting videos here back in 2017.
I'm grateful that you all like to nerd out with me and hope we can keep it going in 2026. In this video, I want to talk about some of the unexpected things that happened in 2025 that I think investors can learn from. I was having a lot of conversations in late 2024 with people who wanted to go all in on the US stock market, either abandoning international diversification entirely or reducing their exposure to Canadian and international stocks in favor of more US exposure.
This wasn't really surprising. At the end of 2024, the US market had been crushing other markets for years. For example, for the five years ending December 31st, 2024, the US market had outperformed the Canadian market by nearly five percentage points annualized. And it outperformed international developed and emerging markets by an even wider margin, all measured in Canadian dollars. And that's just five years. Go back further, 10 years, it was still a big outperformance in the US.
In addition to that, there was plenty of doom and gloom about Canada's stock market and Canada's economy. We had a productivity crisis. We had a proposed hike to our capital gains inclusion rate. Uh capital was fleeing the country when Trump was elected as the 47th President of the United States and started threatening tariffs that could damage Canada's economy further. All of those concerns were exacerbated. I'm not suggesting these are not real economic issues.
They are. But if you had read these headlines and then not looked at the stock market all year, you would probably assume the Canadian market went on to have a terrible year. That assumption would be wrong. As of December 17th, 2025, the Canadian stock market index fund had returned 29.46% since January 1st, 2025, placing it ahead of international developed and emerging markets and more than tripling the Canadian dollar return on a US total market index fund.
Missing a big year like that is hard to come back from. I think there are a couple of important lessons here. One is that the stock market is not the economy. The stock market prices forward-looking information about the expected future cash flows of businesses. The economy does affect those expected future cash flows, but economic data are backward-looking. By the time we hear a headline about Canada's economy, the market has likely already priced it in months prior.
If economic data end up being bad, but better than what the market had been expecting, we can even see a rise in stock prices on bad economic news. It's crazy to think about. This makes basing investment decisions on economic news a pretty bad idea most of the time. The other related lesson is that while the future is hard enough to predict, future stock returns are probably even harder. Some news, like unexpected tariffs, can affect stock prices in the short term.
Looking back to early 2025, it seemed like tariffs would be putting significant downward pressure on all stock markets. Again, the market is always looking ahead. A shock like tariffs can result in stock prices falling on the news, but as new information about the actual impact of tariffs become known, markets adjust. The US stock market was down more than 16% in Canadian dollar terms in April 2025. One of the things I said in a video earlier this year, around that time, looking at historical data for the US stock market, was that negative intra-year returns don't always predict negative returns for the year.
It's not uncommon for stocks to enter negative territory at some point during the year, while then finishing the year with positive returns. And that is exactly what we saw in 2025. This is one of the many reasons that sticking to your long-term plan is generally much better than trying to get in and out of the market or otherwise changing your portfolio based on whatever might be happening in the world around you. I think the other big lesson here is that international diversification is still not dead.
There's been an increasing perception that the US stock market is the only market that anyone needs to invest in. I and many other people smarter than me have been saying for years now that international diversification continues to be one of the most important principles for long-term investors, despite the recent outperformance of the US market. 2025 was a good reminder of why this is true. A single country stock market, including the US market, can go through both short and long periods of poor performance.
The US lost decade wasn't all that long ago, but it's easily forgotten. In those periods, international diversification often pays off, as it did this year. Canada's incredible stock returns this year seem to have largely gone unnoticed. The other story that I've not seen mentioned much is the returns of Canadian value and small-cap value stocks, which have had an even bigger year than the Canadian market as a whole.
The iShares S&P TSX Small Cap Index ETF returned 47.94% from January 1st through December 17th, 2025, and the iShares Canadian Value Index ETF returned 33.63%. I know it doesn't make sense to focus on one year of returns, but the crazy thing here is that if we looked at the data a year ago, the 10-year returns of Canadian value and small-cap stocks trailed the market. Value stocks were only a little bit behind. Small caps were way behind.
Fast forwarding to December 17th, 2025, so now we're looking at just under 11 years of data from the same starting point, Canadian value has now outperformed for the full period, and while small caps are still trailing the market, it's a lot closer than it was. The lesson here is that if you believe in an investment strategy, staying in your seat is extremely important. Returns often come in short spurts. Missing out on them is easy to do if you don't stay invested, and missing out is very hard to recover from.
It's kind of like getting up to pee during a hockey game and missing a big goal. The small cap and value examples are of particular interest to me. While I am a big believer in total market index funds, and I talk about them on the on this channel all the time, that is not how I invest my money or the money of most of PWL Capital's clients. We use funds from a company called Dimensional Fund Advisors, which look a lot like total market index funds, but they tilt toward small-cap, value, and highly profitable companies.
That approach has struggled at times in recent history, but the Dimensional Canadian Equity Funds similarly had a big year in 2025 due to their exposures. People get annoyed when I bring up Dimensional Funds because they're not available directly to DIY retail investors in Canada, but on that point, I have some really good news. Avantis Investors, a direct competitor to Dimensional Fund Advisors, is partnering with CIBC to launch a suite of Canadian-listed ETFs.
Like Dimensional, Avantis Funds are very similar to index funds in principle. They're low cost, broadly diversified, and tax efficient, but they have a more flexible implementation approach, and unlike a total market index fund, which holds stocks at their market capitalization weights, Avantis uses financial economic theory and evidence to tilt toward small-cap, value, and highly profitable stocks. These tilts are designed to increase expected long-term returns.
The big development here is that while Dimensional Funds in Canada are only available through advisors like PWL Capital, Avantis ETFs will be available directly to retail investors. I used US-listed Avantis ETFs in my old model portfolios that were designed to give retail investors in Canada a way to implement this investment approach. I will definitely make a dedicated video when I have something more to talk about.
We do know the fees listed in the preliminary prospectus, which look very reasonable. The Avantis CIBC All Equity Asset Allocation ETF has an annual management fee of 0.28%. This is not the MER, to be clear, the management expense ratio, which includes other costs and taxes in it. For example, XEQT has a management fee of 0.18% and an MER, management expense ratio, of 0.2%. Even if the Avantis fund comes in at 0.35% uh for the MER, it still looks pretty good for what you're getting.
It's like uh like an asset allocation fund that looks a lot like VEQT or XEQT, but it's got built-in tilts toward small-cap, value, and high-profitability stocks. Based on the preliminary prospectus, it will have a long-term strategic asset mix of 45% US stocks, 32% Canadian, 15% international developed, and 8% emerging markets. Again, very similar to an XEQT or a VEQT. This is definitely a development to watch in 2026 if you're as much of a nerd as I am.
To be clear, I'm not affiliated with or being paid by Avantis, and I gain nothing from you using their products in Canada or in the US. I just think this is good news for the nerdiest of us Canadian investors who want an easy-to-use evidence-based alternative to low-cost total market index funds. Gold has had an incredible year. The iShares Gold Bullion ETF returned 57.53% in Canadian dollar terms from January 1st through December 17th, 2025.
I have never been a proponent of holding gold in portfolios for the simple reason that it's not a productive asset with a meaningfully positive expected return. Gold has long-term returns. By long-term, I mean 100 years or longer, roughly in line with inflation, maybe a little higher. Short-term returns will fluctuate wildly around its real value and a mixed track record as a hedge against bad markets and inflation. Its place in a portfolio is not obvious to me unless you have a belief that its price will go up while you hold it, which to be fair worked out great for people who were holding it this year.
As Warren Buffett has said, what motivates most gold purchases is their belief that the ranks of the fearful will grow. It makes sense to buy gold if you think other people are going to want to buy gold in the future. I don't love that reason to invest in something, which is why I don't hold it or suggest holding it. The question I keep getting based on gold's returns this year is whether my views on gold have changed in light of its recent performance.
I am totally open to updating my beliefs when I receive new information, but I would not consider high short-term returns to be sufficient new information to update a prior belief that gold has low expected returns. Academic research using huge amounts of data and applying economic theory suggests that gold has an expected return of around 1% above inflation. And that's on the high end of the estimates I've seen, which is roughly what its historical return has been, at least over the sample period in that paper.
When we look back through history, gold has had big jumps in price before, and the most common outcome of the resulting high gold prices is lower future gold returns, bringing its real value and its long-term returns back in line with its long-term historical performance. I'm not predicting a gold crash, but I think the data on this do warrant caution for anyone who's enticed by its recent returns. If you have been holding gold, congratulations on a great year.
If you're looking at gold's recent high returns and just now considering buying gold, I think it's worth remembering that investors have a tendency to buy things after they have done well and sell after they have done poorly, leading to bad investment outcomes. I don't mean that nobody should invest in gold right now, but I do mean that you should have a very good understanding of why you want to invest in gold right now, other than the fact that it's gone up a whole bunch recently, and keep in mind that the base rate expected long-term return return for gold is low.
Bitcoin went in the opposite direction this year. The Purpose Bitcoin ETF dropped 13.09% in Canadian dollar terms from January through December 17th, 2025. For similar reasons to gold, I've never been a proponent of including Bitcoin in long-term portfolios. This one bad year doesn't prove anything. It doesn't mean I was right. Obviously, Bitcoin's gone up a ton other than this year so far. Uh but Bitcoin's divergence from gold over a period with lots of geopolitical uncertainty, where Bitcoin's kind of meant to shine, was pretty interesting to see.
We'll We'll see what happens in the future. Another story from 2025 that I don't think is getting enough attention is the continued drop in real estate prices and rents in some of Canada's largest cities. It was not that long ago that real estate going up seemed like a constant fact of life in Canada and rents going up. But things like changes to our immigration policies and a rise in interest rates have put a ton of pressure on the demand for housing in some cities.
From the 2022 peak, composite real estate prices in Toronto, that's combining all types of housing in Toronto, had fallen nearly 26% through November 2025. From January through November 2025, so just this year up until November, that drop was 6.5 percentage points. A common narrative that I've heard here is that most of this drop is coming from the tiny shoebox apartments that were overbuilt in Toronto, but the peak to trough drop in single-family homes has actually been a larger in percentage terms than the drop for apartments.
Prices in other cities have been more resilient, but 2025 was a tough year across the board. An interesting related topic is the status of hypothetical renter and owner wealth across Canada. Earlier this year, I did a video and a paper comparing a hypothetical renter and owner in 12 Canadian cities using real data on rents, house prices, inflation, and stock returns from 2005 through 2024. So, I had this hypothetical uh renter who was deciding, do I keep renting or do I buy a house?
And if they kept renting, they invested in the stock market. If they bought, they they bought the house. And then they saved and invested. The renter saved and invested the cost difference between renting and owning over time. Then I just tracked how did their wealth evolve over this full period? The analysis at that time showed mixed results, with renting leading to more wealth in some cities, but not in others. And on average across all cities that I looked at, it was basically a tie.
There was a tiny tiny advantage for owning. I measured the outcome as the ratio of renter wealth to owner wealth, so a number above one means the renters were better off, and below one means the owners were better off. The average owner uh the average renter to owner wealth ratio, as you can see, is uh was 0.99 at the end of 2024. And then so far in 2025, real estate is down, as I mentioned. Rents are flat or maybe down a bit, and stock markets are way up.
I will do a full update once I have the year-end data for 2025, but as of November, renting is beating owning on average across the 12 cities, with an average renter to owner wealth ratio of 1.14. Again, above one means renters have more wealth than owners on average across these 12 cities. In some cities that previously had a huge advantage for owners over renters in the sample, uh like over the original 2005 to 2024 sample, uh Victoria and Kitchener being the big Kitchener-Waterloo being the biggest examples, that gap, the the uh wealth gap between owners and renters, has narrowed to close to zero.
I want to be clear that this does not mean that owning a place to live is bad. I own my house. I've probably taken a beating financially recently, too. I'm okay with that because I like my house. My point on renting and versus owning has always been that renting is not a bad financial decision as long as the renter saves diligently and and invests in a portfolio with sufficiently high expected returns, like a total stock market index fund portfolio. 2025 has put an exclamation point on that point.
Right now, as the year comes to a close, investors seem to be mostly worried about the high valuations and market concentration in the US stock market. The top seven stocks in the US market make up 32% of the market's total value, which is the highest level of market concentration going back to 1927. I don't think that market concentration is something to worry about. Many other countries around the world have had and currently do have more concentrated stock markets than the US market without it resulting in poor returns for those countries.
Even within the US market, the historical relationship between current market concentration and future returns is weak at best and statistically insignificant. High stock valuations could be more of an issue. Historically, looking at 10 developed countries, there is a clear relationship between high current valuations and low future returns. The relationship is not statistically reliable, but it's clearly there. You can see in the chart.
The thing is, even if valuations do have some information about future returns, they do not predict the future. It's possible for high current valuations to be followed by high future returns, as the US market has proven in recent history and other countries have demonstrated in the past. I don't think high stock valuations are a market timing signal. They They don't say you should get out of this stock market right now, but they should lead to more moderate expected returns for that stock market.
When you're thinking about what returns do I expect from this part of my portfolio, a country with high stock valuations, you might want to use lower expected returns, but that doesn't mean that the future returns are actually going to be low, so I wouldn't suggest trying to time the market based on that information. The last comment I have as we close out 2025 is that investors are being increasingly inundated with what I'm calling ETF slop.
Issuers ETF ETF issuers are launching a ton of complex and risky ETFs and marketing them really aggressively to retail investors through influencer campaigns and social media ads. I'm pretty confident saying that most investors don't need Buffett ETFs, which I will do a video on next year, single-stock covered call ETFs, leveraged single-stock ETFs, or leveraged covered call ETFs. Like, what are we even doing? The ETF industry needs to make money, which is fine.
Low-cost index funds are not a profitable business for most ETF issuers. Index funds are literally available for free, at least in one case, from Fidelity. The result is that issuers who want to make money need to come up with products that they can charge higher fees on and that investors will want to buy. We end up with a whole bunch of ETF products designed to cater to the emotional and cognitive biases of investors, not to give them the best chance at meeting their long-term financial goals.
I'm Ben Felix, Chief Investment Officer at PWL Capital. Enjoy the holidays and I'll see you in 2026.
The words are the caption track's own and nothing is reworded or re-transcribed. Paragraph breaks are placed between sentences so the text reads as prose.
Free tools for your own script: paste a draft and see where it stands before you record it.
Paste your draft and see where viewers are likely to drop off, with a rewrite for each weak line.
Paste the first 30 seconds of your own draft for a hook score and rewrites.
Check your draft against YouTube's advertiser-friendly guidelines before you record it.
Read this channel's public videos and transcripts, and download a writing brief for it.